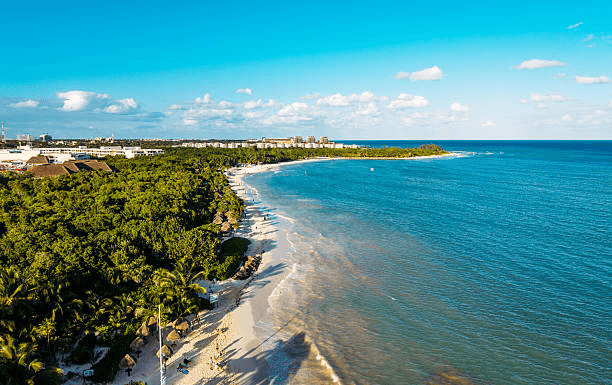
Riviera Maya · Quintana Roo
Playacar Phase II
ESTABLISHEDResidential extension of Playacar with larger lot sizes and lower density. Strong family buyer profile. Growing rental inventory with below-prime pricing relative to Phase I.
Zone intelligence combines verified listing data, participant trust aggregates. Every metric below displays its confidence level. This is market intelligence, not financial advice — confirm figures independently before making investment decisions.
Playacar Phase II presents the structural bones of a credible family-oriented residential hold — gated, low-density, no new supply entering the pipeline — but the investment case rests almost entirely on qualitative inference rather than verified zone data. With 8 active listings, no STR performance data, no days-on-market figures, and zero tracked participants, the platform's coverage for this zone is still in its early stages, and confidence_overall is correspondingly low. The previous overall score of 30.6 and a persistent oversupply characterization set a cautious baseline; until ecosystem coverage and rental yield data mature, Phase II rewards patience over conviction.
Market Snapshot
Prices: Median of 20 current apartment listings (EasyBroker), collected up to 2026-10-06. Asking prices.
Estimated Buyer Composition
AI-synthesized estimate — not derived from transaction registry data
Macro Exposure Matrix
Latest Intelligence Signals
Price history spans only two months — trend interpretation is limited
The tracked price-per-m² of $4,086 USD reflects just two months of data history, which is too short a window to draw reliable conclusions about trend direction. A short-window observation can reflect seasonal listing composition, a single atypical transaction, or genuine price movement — and there is currently no way to distinguish between them for this zone. Confidence in the price signal must be held loosely until the data series matures.
Hurricane season and foreign buyer concentration compound structural risk
Two macro exposures converge in Phase II: Caribbean hurricane risk runs June through November every year without exception, and the buyer pool is estimated to be heavily North American — a concentration that makes demand sensitive to sentiment shifts outside Mexico's control. Neither factor is new to Riviera Maya investors, but both are amplified when zone-level data to stress-test resilience is absent. The combination warrants a conservatively high macro exposure rating.
No participants tracked in this zone yet
The platform has not yet mapped any agencies, developers, or notarios operating in Playacar Phase II — coverage is still building for this zone. This means due diligence on individual transaction counterparties cannot be supported by platform data at this time. Investors active here should rely on independent professional verification until ecosystem coverage expands.
Oversupply regime persists across multiple consecutive cycles
The market regime has been flagged as oversupplied across multiple consecutive scoring cycles, and the current contraction classification is consistent with that reading. A zone can show a rising price-per-m² and still be structurally oversupplied if demand has not absorbed existing inventory — these signals are not contradictory. Until absorption velocity is trackable, the oversupply characterization stands.
Rental yield thesis cannot be independently verified for this zone
Phase II is positioned editorially as a growing rental inventory zone with below-prime pricing relative to Phase I — a reasonable thesis for a yield-seeking investor. The problem is that no STR yield data is tracked for this zone, meaning neither the nightly rate assumption nor the occupancy assumption behind that thesis can be tested. Investors evaluating a rental income strategy here are working from corridor-level analogies, not zone-specific evidence.
Family buyer profile anchors demand without quantified evidence
Phase II's lower-density, larger-lot residential format has historically attracted family-oriented buyers — a cohort that tends toward longer hold periods and less speculative churn. That structural demand anchor is real, but with zero tracked participants and no transaction velocity data available, it remains a qualitative assertion rather than a measurable market force. The family thesis deserves credit; it just cannot be scored with precision yet.
No permit filings eliminate near-term supply addition risk
The absence of any recorded permit activity for Phase II means no new supply is entering the pipeline in the foreseeable term — a modest structural positive in an otherwise oversupplied regime. With only 8 active listings on the platform, the visible inventory pool is thin. Whether that thinness reflects genuine scarcity or simply limited platform coverage is a distinction that matters and cannot yet be resolved.
Oversupply regime persists across multiple consecutive cycles
The oversupply condition is not a single-cycle artifact — it has been flagged across multiple consecutive reporting cycles in the recent signals. No permit activity mitigates near-term new supply pressure, but the existing inventory overhang remains unresolved. Absorption data is absent, so the pace at which this imbalance could correct is entirely unknown.
Rental yield thesis is entirely unverifiable
The editorial description positions Phase II as a growing rental inventory zone with below-prime pricing — a thesis that implies STR or long-term rental yield as part of the return case. That thesis cannot be stress-tested: no nightly rate, occupancy, or yield data exists for this zone in the tracking system. Investors underwriting a yield component here are doing so on faith, not evidence.
No new permits eliminate near-term supply addition risk
The absence of any recorded permit activity in the supply pipeline means no new units are entering the development queue in this zone. This is a mildly constructive supply-side observation — the oversupply problem will not be actively worsened by fresh launches. It does nothing, however, to resolve the existing inventory imbalance.
Zero tracked participants leave due diligence entirely blind
With zero agencies, developers, and notarios mapped in the participant ecosystem, there is no independent verifiability layer for any transaction in this zone. This is not a minor data gap — it means an investor cannot validate a single counterparty through the Riviera Audit framework. Until this ecosystem is mapped, the trust score is effectively a floor, not a nuanced assessment.
Hurricane season and foreign buyer concentration compound structural risk
Two non-diversifiable risk factors overlap in Playacar Phase II: Caribbean hurricane exposure running half the calendar year and a buyer pool that appears heavily concentrated in foreign nationals. A demand-side shock — whether from a direct storm hit, a USD/MXN dislocation, or a shift in US or Canadian buyer sentiment — lands in a zone with no visible domestic demand buffer and an unmapped transaction ecosystem.
The Riviera Maya, measured.